

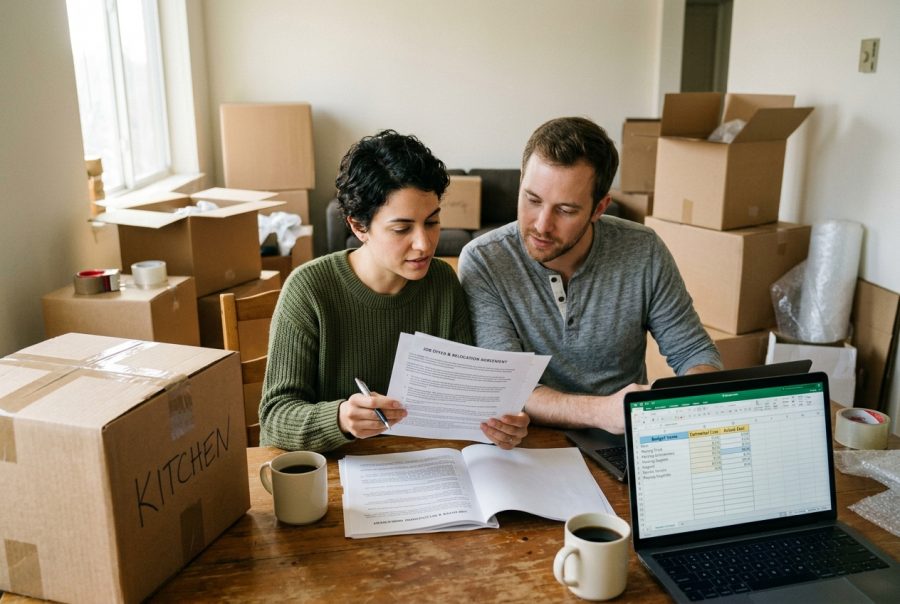
Do not move until three lines are in the offer or a side letter: what they pay, when you would have to pay it back, and what happens if they end the job. A layoff, a reorg, or a rescinded role should not trigger a repayment.
- Prefer a carve-out in writing: no clawback if the company terminates you without cause, including layoff, within the repayment window (often 12–24 months).
- Know the package type. A lump sum you have already spent is the painful one to return. Direct-bill moving costs are usually easier to walk away from.
- Stress-test one bad year before you break a lease or buy: layoff in month 3, partner’s job does not transfer, and a lease you cannot exit.
- Keep 3–6 months of the new city’s essential bills in cash that is not the relocation lump sum.
Relocating for work can be worth it. It is a bad trade when the company can end the role and still send you a bill for the movers. In 2026, repayment clauses are common on lump-sum packages, and “we never enforce that” is not a term. This is general information, not legal, tax, or employment advice. Have an employment lawyer in the destination state read anything you do not understand before you resign your current job.
The wider decision sits in the pros and cons of moving for a job and the job relocation guide. This page is the part people skip: how you get hurt on the way out.
Relocation package clauses
Ask which of these you are being offered. The label on the HR portal matters less than who pays the invoice and who owes money if you leave, or if they make you leave.
| Clause | How it works | Layoff risk | What to ask for |
|---|---|---|---|
| Lump sum | One payment, often grossed up for taxes, for you to spend on movers, travel, and temporary housing | High if you must repay the full sum after you have spent it | Repayment dies if they end the job without cause. Prorate by month if you resign. Cap it at money you have not spent. |
| Reimbursement | You pay vendors, submit receipts, and they pay you back up to a cap | Medium. You carry the cash float. A clawback can still reclaim reimbursements already paid. | A fast reimbursement cycle (15–30 days) and the same layoff carve-out as a lump sum |
| Direct bill | The company pays the mover, the hotel, or the rental car. You may see a managed move through their vendor. | Lower for cash, because the invoice never hit your account. Some contracts still convert those costs into a debt if you leave. | Written confirmation that direct-billed costs are not your debt after a layoff or a rescinded offer |
| Clawback / repayment | If you leave inside 12–36 months, you repay some or all relocation money, sometimes on a sliding scale | The dangerous version also triggers when they lay you off, fail to transfer your visa, or cut the role | Exclude termination without cause, layoff, reorg, role elimination, and a start date they cancel. Get “cause” defined. |
| Lease-break protection | They pay the penalty to exit your current lease, or the penalty if they move you again or end the job | Without it, a layoff leaves you paying rent in a city you moved to for them | They cover the destination lease break if they terminate you without cause inside the first year, up to a stated cap |
Package names differ by employer. The signed offer, relocation policy, and any side letter control. Tax treatment of lump sums and reimbursements is a separate question for a tax preparer.
How Much do Movers Cost?
As Featured On:

Negotiation script
Have this conversation before you give notice and before you sign a destination lease. Email is better than a hallway promise. You can send the wording below almost as written.
You: I am ready to accept and relocate. I need the repayment terms adjusted before I resign and before I break my lease.
You: Please add this to the offer or a side letter: if the company ends my employment without cause, including layoff, reorganization, or elimination of the role, or if the company withdraws the offer after I have started the move, I do not repay relocation funds. That includes the lump sum, reimbursements, and costs you direct-billed.
You: If I resign, repayment should step down monthly across 24 months, and it should never include amounts already paid to tax withholding that I cannot recover.
You: If you terminate me without cause in the first 12 months, the company will pay any documented lease-break fee at the destination, up to two months of rent, and a one-way ticket or mileage home.
Them: Our policy is standard. We do not change clawbacks.
You: Then I need either a direct-bill move with no personal repayment after a layoff, or a higher sign-on that I can keep, separate from relocation, so I can self-fund the move and decline the clawback. I am not able to take on a debt that survives you cutting the job.
Stop talking after that last line. If they need the role filled, someone can write a sentence. If nobody can, you have learned that the package is a loan. Treat it as one. The broader tradeoffs are in the job relocation guide.
Two extras worth asking for, in the same email: a start date that does not force you to move before a background check clears, and a sentence that a delayed visa or license transfer is the company’s problem if the job required it. Do not relocate your family on a verbal “HR says you will be fine.”
Financial stress test
Run your own numbers. The table uses a made-up example so you can see the shape of the risk: a $95,000 salary (about $5,600/month take-home, which varies by state), an $8,000 lump sum, $2,200 rent, and $18,000 in cash that is not retirement money. Replace every figure with yours.
| Scenario | What you live on | Rough runway on $18,000 cash | Decide this before you sign |
|---|---|---|---|
| You keep the job | Full pay. Housing at $2,200 plus about $1,400 essentials (food, utilities, transport, insurance) | Cash stays intact if the new budget actually fits | Go only if rent plus utilities is at or under 30% of gross and the job is real |
| Laid off in month 3, clawback applies | Maybe a short severance. You may also owe the $8,000 back. | Under 4 months of essentials, and shorter if you repay the lump sum | Do not accept unless the clawback is carved out for layoff |
| Laid off in month 3, no clawback, 8 weeks severance | Severance plus cash. Rent still due unless they pay the lease break. | About 5–7 months if you cut spending and do not repay movers | Acceptable only with lease-break help or a lease you can exit |
| Partner’s income does not come with you | One paycheck in a city you priced for two | Fine if you qualified for the lease alone. Dangerous if you did not. | Sign housing you can carry on the lower income |
| Offer pulled after you gave notice | Old job may already be gone. Moving bills may already be real. | Whatever cash you did not spend on a non-refundable deposit | Do not resign until the offer is signed, contingencies are clear, and deposits are refundable |
Example only, not a forecast of your taxes, severance, or unemployment eligibility. Unemployment rules depend on the state and on why the job ended.
Before you sign a lease
- Price the move itself on the moving cost estimator. A “we will cover reasonable expenses” line is not a budget.
- Rent something you can leave. A month-to-month, a six-month term, or a written job-loss clause beats a perfect apartment with a 14-month penalty.
- Do not buy a house to celebrate a relocation. Buying converts a layoff into a second sale.
- Keep the lump sum in a separate account until the move is done, so you can repay it if you have to. Spending it on furniture and then owing it back is the trap.
- If your partner does not want to go, settle that with a date and a return plan. The compromise strategies are the other half of this decision.
- If you arrive and the job or the city is wrong, use a 90-day regret plan and read the clawback again before you resign.
Frequently asked questions
Can an employer make me repay relocation money if they lay me off?
Sometimes, if you signed a clause that says so. Many do not distinguish between you quitting and them cutting the job. Ask for a written exception for termination without cause, layoff, and reorg before you accept. An employment lawyer in that state can tell you whether a clause you already signed is as broad as it looks.
Is a lump sum better than a reimbursed move?
A lump sum is simpler and easier to spend on the wrong things. Reimbursement and direct bill leave a paper trail and often a lower personal debt if you negotiate the clawback. The best package is the one you do not have to return after they end the role.
Should I resign before the relocation agreement is signed?
No. Wait for the signed offer, the repayment language, and a clear start date. A background check, a license, or a visa that is still open is a reason to delay notice, not a reason to “show commitment” by quitting.
How much cash should I hold back?
A practical target is 3–6 months of essential bills in the new city, kept separate from the relocation payment. If the only way the move works is spending the lump sum and hoping the job lasts, the stress test has already failed.
What if they will not change the clawback?
Then decide with your eyes open. Self-fund the move and decline the repayable benefit, ask for a sign-on that is yours to keep, or stay. A standard policy is still a choice. It is not an order to take on the debt.
Job relocation next steps
Also Read
Office Moving Checklist: How to Plan the Perfect Office Move
Moving to a new office can be a serious task for a business - an office relocation job that often proves to be... Read More
Boston Moving Guide – Info and Advice
History, culture, green open spaces, and a thriving economy await you in Boston Boston is one of the most... Read More
10 Hot Tips for Moving in the Summer
It’s no secret that summer is the most popular season to move house – the weather is usually nice (warm and dry),... Read More
More about the author

Martin is a moving expert and online marketer who’s been involved in the moving industry since 2004. Writes for MoveAdvisor, formerly MyMovingReviews.com.

Manuella is a moving expert featured in Forbes, USA Today, Zillow, The American Moving & Storage Association. Writes for MoveAdvisor, formerly MyMovingReviews.com.
Posted on
Discussion 0 comments
Leave a comment