She owns a home worth $500,000. The mortgage is finally paid off. She has another $100,000 in savings and retirement accounts, and around $2,700 a month coming in from Social Security and other retirement income.
On paper, Linda is worth roughly $600,000, but she certainly doesn’t feel like it.
The property-tax bill still arrives. Homeowners insurance keeps getting more expensive. The furnace is getting old. The roof won’t last forever. Food costs more. Healthcare costs more.
And more than 80% of Linda’s wealth is tied up in the house she is sitting in.
She can’t use a bedroom to pay for groceries or hand the pharmacist part of her kitchen.
Her home may be worth half a million dollars, but unless Linda sells it or borrows against it, most of that money is effectively locked away.
Linda is house rich and cash poor.
And there are plenty of Lindas in America.
Among homeowners aged 65 and over, median home equity was $250,000 in 2022. For older homeowners in the lowest income quartile, median equity was $115,000, but that represented 67% of their total assets.
That creates a strange retirement problem.
You can spend 30 years building wealth and arrive at retirement with hundreds of thousands of dollars to your name, yet still worry about whether you can afford a $10,000 home repair.
So what are you supposed to do with the house?
Keep it?
Downsize?
Sell and rent?
Borrow against it?
Leave it to the children?
Or finally start spending some of the wealth you spent decades building?
Let’s see what happens to Linda.
Linda Could Need This Money for Another 20 or 30 Years
Retirement isn’t necessarily a short final chapter.
CDC reports that a 65-year-old American could expect to live another 19.7 years on average in 2024. For women, it was 20.8 years; for men, 18.4.
But an average is just that. Plenty of people who retire in their mid-60s will live into their 90s.
At the same time, the average monthly Social Security benefit for a retired worker was about $2,087 in October 2026.
Social Security isn’t necessarily a retiree’s only income, of course. But the figures help explain how someone can own an extremely valuable asset and still have relatively little money passing through their checking account each month.
Linda doesn’t simply need somewhere to live.
She potentially needs to finance another two or three decades of life.
And the biggest asset she owns is her home.
How Much do Movers Cost?
Save up to 40% on your upcoming move and get a quote from reputable moving experts.
This is where the house-rich, cash-poor problem becomes interesting.
Linda did what generations of homeowners were told to do.
She paid off the mortgage before retirement.
So her housing is free now. Except it isn’t.
A mortgage-free homeowner may still have to pay for:
Property taxes
Homeowners insurance
Utilities
Repairs and maintenance
HOA fees
Landscaping or snow removal
A new roof, HVAC system, windows, or appliances
Accessibility changes later in life
Those non-mortgage costs have been rising quickly.
Between 2019 and 2024, median housing costs for households that owned their homes free and clear increased by 35%, according to Harvard’s Joint Center for Housing Studies.
Let’s make Linda’s situation more concrete.
Imagine that property taxes, insurance, and normal maintenance on her home work out at an average of $13,500 a year.
That’s not a national average; we’re simply giving Linda a plausible, hypothetical budget to see what happens.
It works out at $1,125 a month before utilities.
Suddenly a “free” house is costing a fair chunk of Linda’s $2,700 monthly retirement income.
Then one year she needs a new roof.
Linda can be wealthy enough to own a $500,000 asset and still have to worry about a five-figure repair bill.
Some Retirees Are Still Paying the Mortgage Too
Linda is actually ahead of many older homeowners because she has cleared the loan.
That traditional milestone is becoming rarer.
Among homeowners aged 65–79, the share still carrying a mortgage increased from 24% in 1989 to 41% in 2022. The median mortgage debt among those borrowers rose from $21,000 to $110,000 in inflation-adjusted dollars.
Having substantial home equity, therefore, doesn’t necessarily mean having low housing costs.
For Linda, however, the loan is gone.
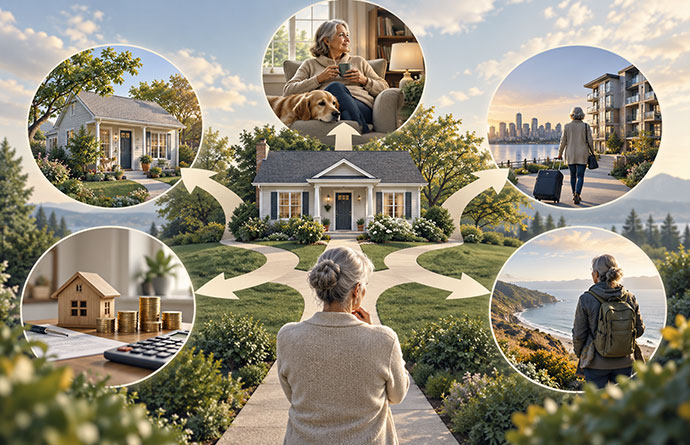
She now has five potential choices.
What Could Linda Do With Her $500,000 Home?
Before we look at each one, here is the problem in one table.
For argument’s sake, we’ll assume Linda’s situation looks like this:
Age: 67 Home: $500,000, mortgage-free Other savings/investments: $100,000 Retirement income: $2,700 a month
The selling and moving costs below are hypothetical rather than national averages. They are there to make the choices easier to compare.
Linda’s choice
What happens to the house?
Approx. liquid assets immediately after the move*
What changes?
Stay
Keeps $500k home
$100,000
Maximum housing equity, minimum disruption
Downsize to $300k home
Sells and buys smaller
~$260,000
Unlocks about $160k while remaining an owner
Sell and rent
Sells, doesn’t buy again
~$565,000
Maximum liquidity, but lifelong rent
Access equity
Keeps home
Depends on product
Gets cash without moving, but creates debt
Sell and live flexibly
Sells, no permanent replacement home
~$565,000
Maximum flexibility, but no permanent home base
*Illustrative only. Actual proceeds depend on sale price, transaction costs, taxes, moving expenses, financing, and the replacement property.
The interesting thing is that Linda’s net worth hasn’t suddenly transformed.
What changes is where the money sits and how easily she can use it.
And that could completely change her retirement.
Linda Stays Exactly Where She Is
This is probably the most common option, partly because it doesn’t feel like an option at all.
Linda simply stays where she is.
There are good reasons to do that.
She knows the neighborhood.
Her friends may live nearby.
She knows where the grocery store is, who her doctors are, and which neighbor will collect a package if she isn’t home.
There are no moving costs, no packing, and no emotional upheaval.
And she continues to own an asset that may appreciate.
But financially, Linda hasn’t chosen to “do nothing.”
She has chosen to keep roughly $500,000 invested in one property.
She must continue paying the associated costs of that property, and that $500,000 remains largely unavailable for everyday spending unless she later sells or borrows against it.
There is also another question that is easy to ignore at 67.
Will this still be the right house at 77? What about 87?
Four bedrooms may have made sense when children lived at home.
A big yard may have been a pleasure at 45.
Stairs may be easy to use today.
But a home designed around one stage of life can become expensive, inconvenient, or impractical in another.
So you have to ask not only if you can afford to stay, but also, am I paying to maintain a house for a life I no longer live?
For someone who has lived in the same home for decades, downsizing often starts long before moving day. Deciding what to keep, sell, donate, or give to family can be one of the hardest parts. Our decluttering-before-moving guide walks you through that process.
Linda Downsizes
Sell the $500,000 home.
Buy something smaller for $300,000.
Pocket $200,000.
Problem solved.
Except Linda doesn’t really pocket $200,000.
Selling costs money. Moving costs money. The home may need work before listing. There may be costs associated with buying the next property.
For our example, let’s assume that after the whole process Linda releases $160,000.
Her accessible savings and investments rise from $100,000 to around $260,000.
She still owns a home.
She may also cut property taxes, insurance, utilities, and maintenance.
On paper, it looks like a very sensible middle ground.
But downsizing comes with its own trap.
The smaller home got more expensive too.
Linda may discover that the two-bedroom townhome or condo she imagined moving into now costs far more than expected.
And moving into a condo to eliminate yard work and exterior maintenance may simply replace those costs with a monthly HOA fee.
If the smaller home is an apartment or condo, the transition can require more planning than simply choosing fewer rooms. See our guide to moving from a house to an apartment.
That’s why anyone considering downsizing needs a different calculation, one that answers this question:
How much cash will I actually have left after I sell this home, buy the one I want, and complete the move?
If Linda goes through the entire process and frees $160,000, she may decide that’s worthwhile.
If the real number turns out to be $40,000, she may feel very differently.
Downsizing itself can also be more complicated than it sounds, particularly when decades of belongings have to fit into a much smaller home. Our guide to How to downsize when moving covers the practical side, from deciding what to keep to planning the space in your new home.
The Part Retirement Calculators Often Miss – The Move Itself
If Linda decides to downsize, the financial calculation doesn’t end with the two home prices.
There is also the practical cost of leaving a home she may have lived in for decades.
She may need movers. She may need professional packing. She may need temporary storage if the sale and purchase don’t line up. Large furniture that worked in a four-bedroom house may not fit into a condo. Decades of possessions may need to be sold, donated, or divided among family members.
And for an older homeowner, the cheapest move is not necessarily the best move. Paying for packing, furniture disassembly, or a full-service mover may be worthwhile if it reduces physical strain and stress.
That’s why the real downsizing equation is:
Sale proceeds − replacement home − transaction costs − moving costs − setup costs = money actually released
Professional movers, packing, storage, and additional services can materially reduce the amount left over, especially on a long-distance move. See our breakdown of how much moving costs before estimating how much downsizing will actually release.
Linda Sells and Rents
Now the numbers change dramatically.
Let’s say Linda sells the $500,000 home and, after our hypothetical selling and moving costs, has $465,000 left.
Add her existing $100,000.
Linda now has approximately $565,000 in liquid savings and investments.
Yesterday, most of her wealth was locked in a building.
Today, she can actually access it.
But she has created something she didn’t have before: Rent.
Suppose Linda pays $2,000 a month in rent.
That’s $24,000 a year.
If we deliberately make the calculation extremely simple — ignoring investment returns, inflation, and future rent increases — the $465,000 released from her home would pay for about:
19 years and 4 months of $2,000 rent.
Linda is 67.
That takes her to roughly age 86.
That’s not an argument against renting. Linda would still have her other income and investments, and sensible investing could change the calculation considerably.
But it exposes the trade-off beautifully.
Linda has exchanged a valuable asset + ownership costs for accessible capital + an ongoing rental bill.
And older renters already face considerable affordability pressure.
Selling the house therefore doesn’t make the housing problem disappear.
It changes its shape.
There is no roof replacement.
No property-tax bill.
Possibly no yard to maintain.
But there is also no final mortgage payment after which rent disappears.
Rent can continue for as long as Linda does.
What If Linda Wants the Money but Doesn’t Want to Leave?
This is where the conversation gets more complicated.
Linda’s choices aren’t limited to keeping the house and remaining cash poor or selling the house and accessing the money.
She may be able to borrow against the equity instead.
Depending on her finances and circumstances, possibilities can include a home-equity loan, a HELOC, or a reverse mortgage.
For someone like Linda, the reverse mortgage is particularly interesting because it was designed around this exact contradiction: an older homeowner who has significant equity but wants access to some of it without selling.
The most common reverse mortgage is the federally insured Home Equity Conversion Mortgage, or HECM, available to qualifying homeowners aged 62 and older. The homeowner retains title to the property and normally doesn’t make monthly mortgage payments. Instead, interest and fees are added to the balance, so the amount owed grows over time.
That sounds attractive for Linda.
She keeps living in the house.
She gains access to some equity.
She doesn’t have to rent.
But there is no free-money trick here.
Linda must continue paying property taxes and homeowners insurance, keep the home in good condition, and use it as her principal residence. The growing loan balance also means less home equity remains over time.
So Linda has again made a trade.
She has turned some future home equity into money she can use today.
Which raises perhaps the most uncomfortable question in this entire article.
Who Exactly Is Linda Saving the House For?
Imagine Linda decides never to touch the equity.
She stays in her home for another 23 years and dies at 90.
Perhaps the house is worth considerably more by then.
Her children inherit it.
That could be exactly what Linda wants.
There is enormous value in leaving something substantial to your family, particularly if passing wealth to the next generation is one of your priorities.
But consider another version of Linda’s retirement.
For those same 23 years, she worries about money.
She doesn’t take the trip because it seems extravagant.
She thinks long and hard before hiring someone to help around the house.
She avoids spending from her relatively small savings because she is frightened of running out.
All the while, she has hundreds of thousands of dollars tied up in the property.
And then her adult children inherit it.
There’s nothing wrong with that outcome.
But Linda should at least have chosen it.
There is a big difference between:
“I want my children to inherit as much of this house as possible.”
and:
“I never really considered the house part of the money I could use.”
Perhaps the home is primarily an inheritance.
Perhaps it’s Linda’s reserve for future long-term care.
Perhaps it provides the financial security that allows her peace of mind.
Or perhaps Linda spent decades paying for it precisely so that one day it could make retirement easier.
Those are very different purposes.
What If Linda Doesn’t Replace the House at All?
Here’s the more radical version.
Linda sells.
But she doesn’t downsize.
And she doesn’t sign a traditional year-long lease somewhere else.
For most of adult life, our housing decisions are constrained by things that may disappear in retirement.
A job dictates the city.
A commute dictates the neighborhood.
Children dictate the number of bedrooms.
Schools dictate the ZIP code.
Then suddenly Linda retires, and many of those rules vanish.
She could spend longer periods near family.
She could take furnished rentals for several months at a time.
She could travel.
She could divide the year between different places.
She could eventually settle somewhere entirely different.
But this is not automatically cheaper than keeping a home or renting one.
It can also introduce its own complications around healthcare, insurance, taxes, possessions, mailing addresses, and simply the very human desire to have somewhere that feels like home.
It may also become far less appealing if mobility or health deteriorates later.
But financially, it raises a fascinating question.
After spending decades accumulating housing wealth, does Linda still need to keep most of her wealth invested in permanent housing once the reasons she bought the house have changed?
For some retirees, the answer will absolutely be yes.
For others, maybe not.
Linda’s $500,000 House Isn’t Really $500,000 She Can Spend
This is the strange thing about home equity.
Linda can open a property website and see an estimated value of $500,000.
She can include $500,000 when calculating her net worth.
She can tell herself that she has done well financially.
And she has.
But there is a real difference between wealth and spendable wealth.
Linda can’t use $500,000 while simultaneously keeping all $500,000 inside the house.
To turn that value into spending power, something has to change.
She has to:
Sell all of it,
Sell and buy something cheaper, or
Borrow against some of the equity.
Each solution gives Linda access to money.
Each also takes something away.
There is no option where she keeps the entire house, unlocks the entire $500,000, and takes on no new cost or risk.
That’s why this isn’t really an article about whether selling is better than staying.
It’s about choosing what you want the home to do for you.
When the Numbers Stop Being the Whole Story
I’m 61. Until recently, I thought of myself as fit, healthy and, if I’m honest, almost immortal.
My home is paid off. I will have a good pension. On paper, retirement looks like it will be comfortable.
Then last year I had a stroke.
It wasn’t a major one, thankfully, but it was enough to change the way I look at all those carefully accumulated assets.
A paid-off house, pension pots, and savings still matter, of course. But suddenly the question isn’t simply, “How much will I have when I retire?”
It becomes, “How much healthy time will I have to enjoy it?”
That experience has made me think differently about the balance between preserving every dollar for later and actually using some of what I’ve built while I’m fit enough to enjoy it.
Financial security matters enormously.
But so does recognizing that none of us are guaranteed the retirement timeline we have penciled into a spreadsheet.
And as the saying goes, a shroud has no pockets.
The House-Rich, Cash-Poor Test
If you’re approaching retirement with substantial home equity, five questions may tell you more than the home’s estimated value does.
1. What does the house really cost me each year?
Include taxes, insurance, utilities, maintenance, HOA fees, and an allowance for major repairs, not just the mortgage.
2. How much of my total wealth is trapped in the house?
If your home represents 20% of your assets, the situation is very different from someone with 80% or 90% of everything they own tied up in it.
3. If I downsized, how much cash would I actually release?
Calculate the replacement home and all the costs of moving rather than simply subtracting one listing price from another.
4. Am I deliberately preserving the home as an inheritance?
There is no wrong answer.
But it should be a conscious decision.
5. Is this still the house I would choose for my next 20 years?
Forget what it meant when you bought it.
Would you choose its size, layout, maintenance burden, and location today?
If not, the financial question may be only half the reason to consider moving.
And if those answers lead you toward moving, don’t start with the boxes. Our week-by-week moving timeline begins about eight weeks before moving day and covers the decisions and tasks in order.
So, What Should Linda Do?
There isn’t one correct answer.
And that’s precisely the point.
If Linda loves her house, can comfortably afford it, and values stability above everything else, staying put may be worth far more than whatever she could release by moving.
If she wants a smaller home and less maintenance, downsizing could convert part of her property wealth into money she can actually use.
If she wants maximum flexibility, selling and renting could unlock most of the equity, but she would be accepting rent for the rest of her life.
If she desperately wants to remain in the house but needs more cash flow, accessing some equity may be worth investigating carefully.
And if her priority is enjoying the money she spent decades building rather than maximizing the estate she leaves behind, she may decide that keeping every dollar inside the home no longer makes sense.
The first decision isn’t whether to sell; it’s more fundamental than that: What is your house for now?
Is it your home?
Your emergency fund?
Your long-term-care reserve?
Your children’s inheritance?
An investment?
Or an asset you spent 30 years building so that one day you could actually use it?
For someone like Linda, getting that answer right could matter far more than knowing whether her home is worth $450,000, $500,000, or $550,000.
Because being worth half a million dollars and being able to live like someone with half a million dollars are two very different things.
And nobody knows what the future may hold. House prices can crash, stocks and shares can go down, but the value of being healthy and having choices is priceless.
*At MoveAdvisor we will connect you with a professional moving company. Please note that we may not be affiliated with
and you may be speaking with another licensed provider.
We use cookies to optimise your experience.Accept and close or Learn more



Share your thoughts by leaving a comment